


Mi Material IPO: Beyond the Headline Numbers
Mi Material makes something most people will never see: precision solder spheres that form electrical connections inside semiconductor packages. It is a small component with a demanding job, and that makes the company’s product mix worth examining.
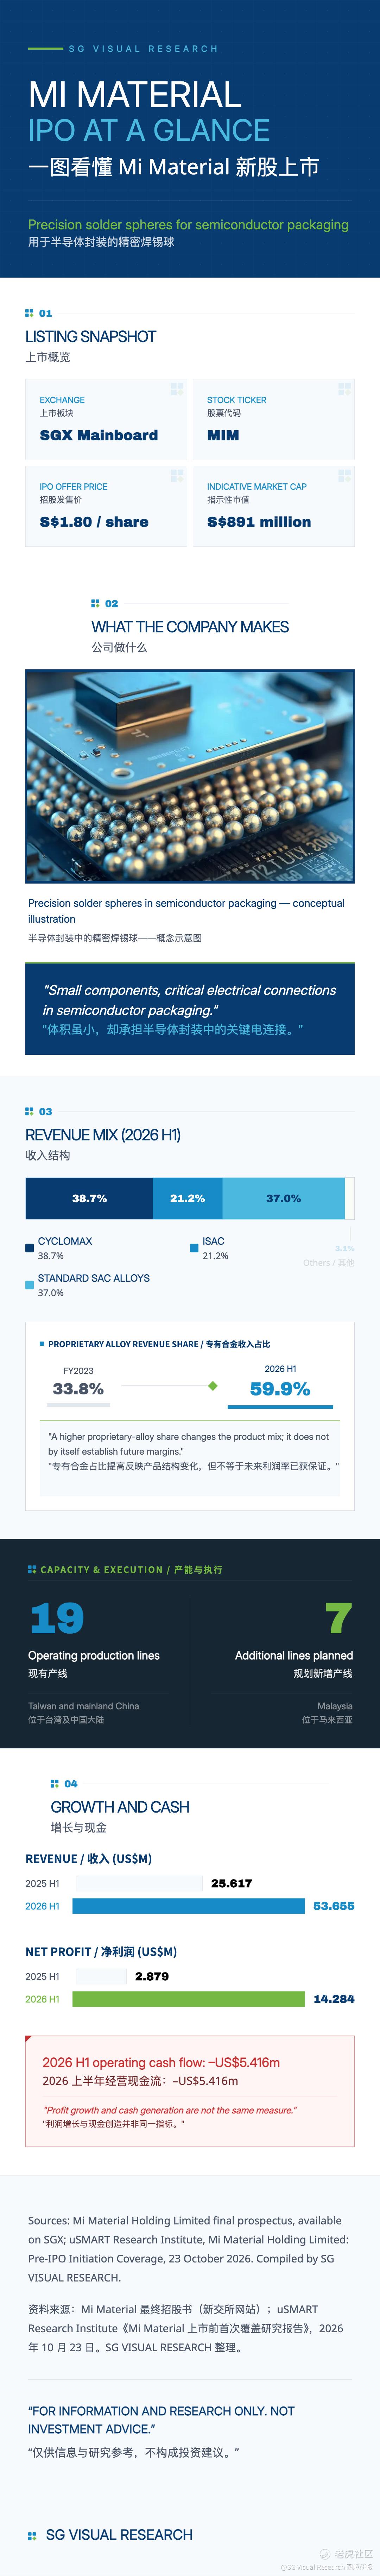
Cyclomax and iSAC, its proprietary alloys, accounted for 59.9% of revenue in the first half of 2026, compared with 33.8% in FY2023. That shift says more about the business than the number of products it sells. The question is whether a richer mix can be sustained as production scales.
The financial figures show both momentum and a test ahead. First-half revenue rose from US$25.617 million in 2025 to US$53.655 million in 2026; net profit rose from US$2.879 million to US$14.284 million. Yet operating cash flow in the first half of 2026 was negative US$5.416 million. Profit growth and cash generation are not the same thing.
Mi Material has 19 operating production lines in Taiwan and mainland China, with seven additional lines planned in Malaysia. The next evidence to watch is not the plan alone, but customer qualification, production ramp-up and cash conversion.
Sources: Mi Material’s final prospectus; uSMART Research Institute, Mi Material Holding Limited: Pre-IPO Initiation Coverage, 23 October 2026.
For information and research only. Not investment advice.
免责声明:上述内容仅代表发帖人个人观点,不构成本平台的任何投资建议。
